Tag: Office of the CFO

  • Risk: Managed or Missed? Four Structural Gaps Reshaping Working Capital Risk 

    Risk: Managed or Missed? Four Structural Gaps Reshaping Working Capital Risk 

    Executive Summary

    Two-thirds of organizations managing working capital are operating with fragmented data, limited visibility and insufficient funding resilience as portfolio complexity outpaces infrastructure. GSCF identifies four structural gaps that can increase risk as working capital programs scale: Visibility, Credit, Buyer Adoption and Integration.

    • Visibility gaps can obscure aggregate portfolio exposure. Organizations may have strong insight into individual programs while still lacking a connected view across funders, counterparties and financing structures.
    • Credit gaps can restrict access and diversification. Traditional funding parameters may exclude viable counterparties that could be served through alternative capital or different funding structures.
    • Buyer adoption gaps can limit portfolio performance. Low participation can leave liquidity untapped and increase concentration among a smaller group of counterparties.
    • Integration gaps can delay decisions. Disconnected systems and workflows increase the time required to move from new information to funding or risk action.
    • Closing the gaps requires connected portfolio control. Bringing programs, data, workflows and capital together gives organizations greater visibility, consistency and oversight as working capital portfolios scale.

    Four Structural Gaps Reshaping Working Capital Risk

    As portfolios expand across funders, geographies and financing structures, the distance between what organizations know and how quickly they can act continues to grow.   

    Closing that gap requires looking beyond individual programs and across four areas that create structural risk: Visibility, Credit, Buyer Adoption and Integration. Together, they provide a framework for evaluating whether an organization’s operating model is keeping pace with the complexity of its working capital portfolio.  

    1. The Visibility Gap : Building a complete view of portfolio risk  

    As working capital portfolios expand, information often becomes increasingly fragmented across different programs, funders, platforms, geographies and financing structures.  

    Teams may have strong visibility into individual programs while still lacking a connected view of aggregate exposure across the broader portfolio. The immediate impact may be slower reporting, but the larger concern is that risk can build before anyone has a complete picture.  

    GSCF’s 2026 research with The Working Capital Forum found that 43% of organizations still rely on fragmented data that requires manual consolidation before decisions can be made, with another 14% dependent on partial consolidation and periodic reporting. Nearly two-thirds of organizations fall into what the research classifies as “Opaque and Exposed” – combining weak visibility with limited funding resilience.  

    Without portfolio-level transparency, individual programs may appear to operate within approved limits while aggregate exposure across the portfolio exceeds institutional risk appetite.  

    Closing the Visibility Gap requires a connected portfolio view that allows organizations to see exposures across programs, counterparties and funding structures, identify emerging concentrations earlier and understand how decisions in one area may affect the broader portfolio.  

    The question to consider:  
    Can we see our total working capital exposure across programs, funders and structures when decisions need to be made?  

    2. The Credit Gap : Expanding access while maintaining control  

    Supply chain resilience depends on more than an organization’s strongest counterparties. It also depends on the middle-market suppliers and buyers that keep the whole ecosystem moving every day.  

    Yet many businesses continue to face barriers to accessing trade finance. The IMF’s Global Financial Stability Report has documented how tighter bank lending conditions push viable borrowers toward alternative funding sources - not because of credit quality, but because conventional bank models were not designed to efficiently serve a wider range of credit profiles. The persistence of that dynamic points to a structural challenge, not a temporary one.  

    The implications extend beyond reduced access to financing. Excluding these counterparties can increase concentration among a smaller group of participants, weaken supply chain resilience and limit opportunities to build a more diversified working capital portfolio.  

    Organizations are therefore looking at how they can expand access to funding while maintaining the controls and oversight required to manage risk effectively. Increasingly, that means combining bank funding with alternative capital and co-origination models that can accommodate a broader range of counterparties without compromising portfolio oversight.  

    The objective is not to eliminate exposure altogether, but to make more informed capital allocation decisions based on a complete understanding of the portfolio.  

    3. The Buyer Adoption Gap : Connecting participation to portfolio performance  

    Every working capital program depends on participation. Even a well-designed and well-funded program delivers limited value if eligible participants never fully enroll.  

    As programs expand across business units, regions and counterparties, driving participation can become more complex. Participants need to understand the value of the program, while communication, documentation and onboarding requirements can create additional friction.  

    Our 2026 research with The Working Capital Forum reinforces the importance of this challenge, with counterparty onboarding complexity emerging as one of the most frequently cited operational risks. Addressing the gap requires more than simplifying onboarding. Buyers also need a clear reason to engage, whether through early payment opportunities, extended terms or other benefits that support their working capital objectives.  

    Low participation may initially appear to be an adoption challenge, but it can have broader portfolio implications. When only a portion of eligible counterparties participates, liquidity remains trapped, funding becomes concentrated among the same buyers and the portfolio may never achieve the diversification it was designed to deliver.  

    Organizations looking to scale participation need to address both sides of the equation: a compelling reason to participate and a simple path to enrollment. That means clearly communicating the value of the program, simplifying the participant experience, standardizing onboarding and removing unnecessary friction.  

    Participation, therefore, should be viewed not only as a measure of program adoption, but also as an important component of portfolio resilience.  

    The question to consider:  
    Are we giving eligible participants a compelling reason to participate and making it easy for them to do so?  

    4. The Integration Gap : Shortening the distance between insight and action  

    In working capital, having access to information is only part of the equation. Organizations also need to be able to act on that information quickly.  

    Working capital teams often spend significant time gathering, reconciling and validating invoices, funding and exposure data across disconnected systems before decisions can be made.  

    Our 2026 research with The Working Capital Forum found that while 59% of organizations have integrated their core systems or achieved high integration supported by automated controls, not a single respondent reported the most advanced level of integration: full connectivity supported by analytics and scenario capabilities.   

    Disparate systems contribute to the challenge, but the larger issue is the delay they create in decision-making. Organizations are increasingly looking to shorten the time between insight and action by connecting data, workflows and approvals across the portfolio.  

    When information moves more seamlessly, exposures can become visible sooner, funding decisions can happen faster, and teams are better positioned to respond before emerging issues become larger risks.  

    The value of greater integration isn’t speed alone. It gives organizations access to connected information while there is still time to act on it.  

    Assessing the Gaps  

    The four gaps provide a practical framework for evaluating whether an organization’s working capital infrastructure is keeping pace as programs scale. 

    These challenges are also interconnected. Limited integration can make it harder to achieve portfolio-level visibility. Poor visibility can lead organizations to take a more conservative approach to credit. Restrictive funding structures or difficult onboarding can limit participation, which in turn can increase concentration.  

    Addressing one gap in isolation may provide incremental improvement, but it does not necessarily solve the broader challenge.  

    Moving Toward Connected Portfolio Control  

    Closing these gaps requires organizations to think differently about how working capital programs are managed.  

    Historically, individual programs have often been managed through separate systems, processes and funding structures. That approach becomes more difficult to sustain as portfolios grow in size and complexity.  

    A more connected operating model brings programs, data and workflows together so organizations can manage working capital at the portfolio-level rather than through a collection of individual programs.  

    This evolution involves moving from fragmented information and processes toward greater connectivity, consistent controls and more timely decision-making. The goal is not simply to collect more data or automate more processes. It is to give decision-makers a clearer understanding of the portfolio and greater control over how capital is deployed.  

    Closing the Gaps  

    Working capital risk can develop through issues that appear relatively manageable when viewed independently, whether it’s a fragmented report, a disconnected workflow, a supplier that cannot access funding or a buyer that never completes enrollment.  

    As portfolios scale, these issues can combine to create structural gaps that limit visibility, increase complexity and make emerging risk more difficult to identify.  

    Organizations addressing this challenge are building operating models around portfolio-level transparency, broader capital access, simplified participation and more connected decision-making. These capabilities can help close the Visibility, Credit, Buyer Adoption and Integration gaps before they become measurable business risks.  

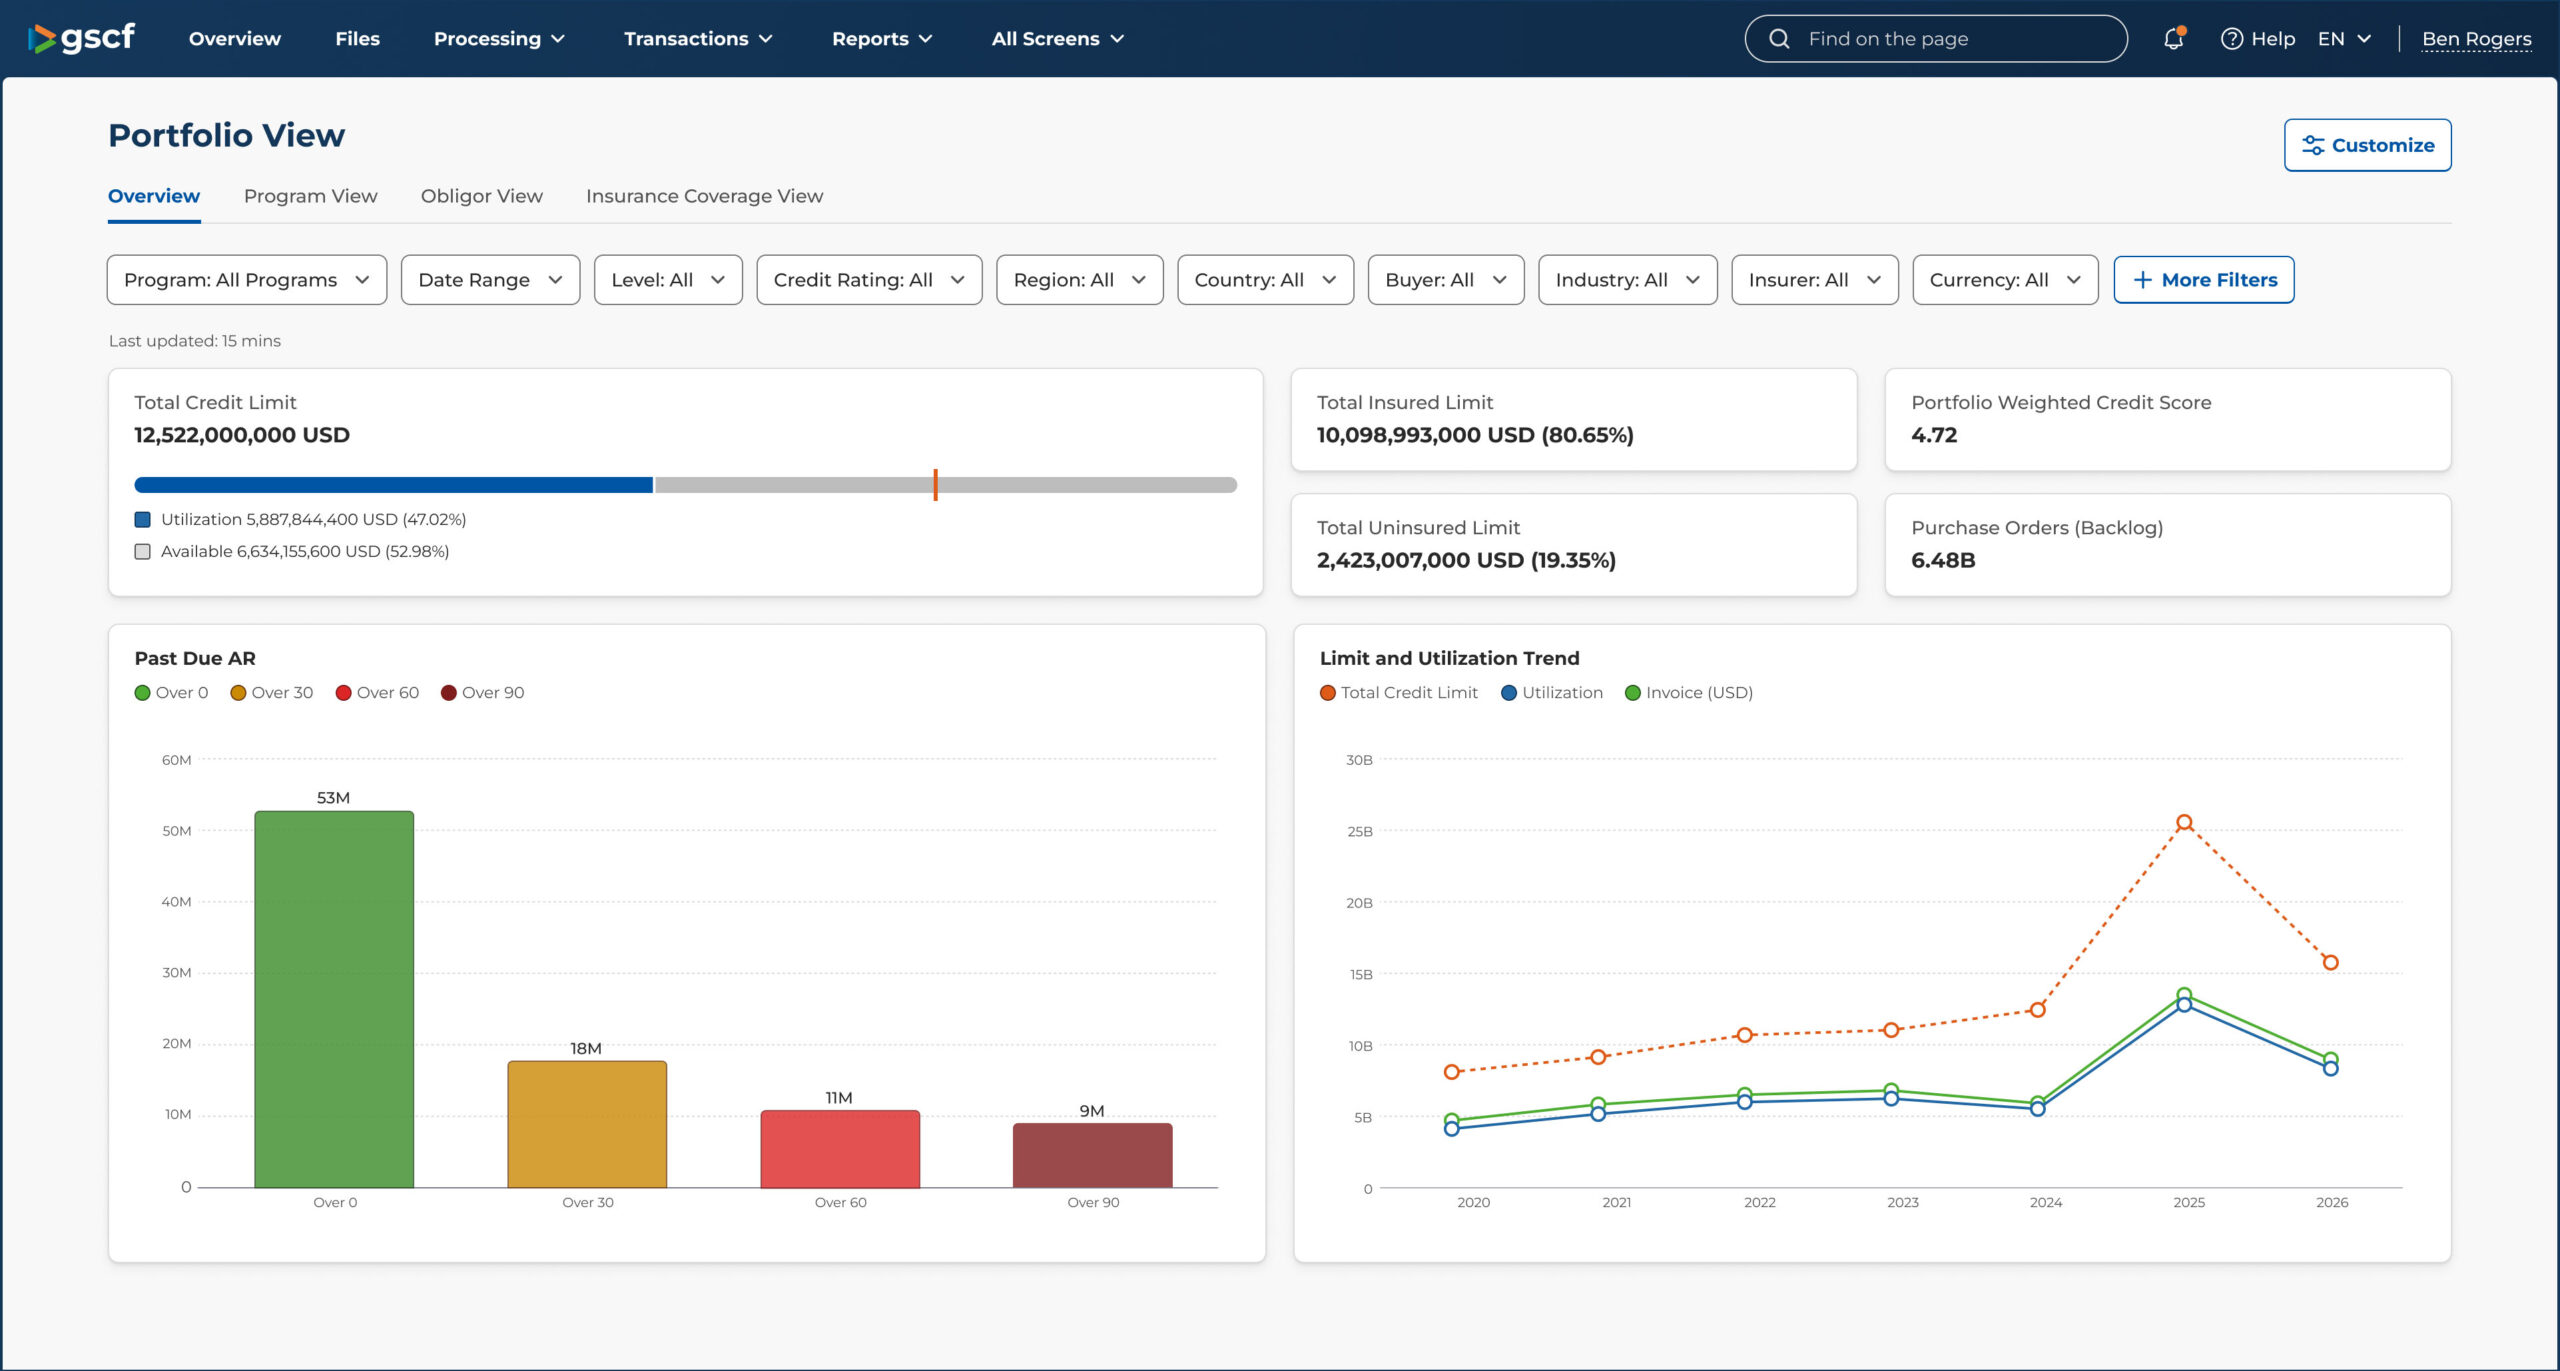
    GSCF’s C4: Connected Capital Control Center, was built to support this approach through a single connected environment for originating, managing and analyzing working capital programs. By connecting programs, data, workflows and alternative and bank capital, C4 helps organizations manage growing working capital portfolios with greater consistency and oversight.  

    As working capital becomes more complex, effective risk management will increasingly depend not only on evaluating individual exposures, but also on having the infrastructure and information needed to understand and manage risk across the portfolio.  

    Ready to close the Visibility, Credit, Buyer Adoption and Integration gaps across your working capital portfolio? See how C4 helps organizations manage working capital at scale.

    Frequently Asked Questions

    1. What are the four structural gaps in working capital risk? The four structural gaps are Visibility, Credit, Buyer Adoption and Integration. Together, they provide a framework for assessing whether an organization’s working capital infrastructure is keeping pace as programs grow in size and complexity.
    2. Why is portfolio-level visibility important in working capital? Portfolio-level visibility provides an aggregated view across working capital programs, funders, counterparties and financing structures. This helps organizations better understand aggregate exposure and identify emerging concentrations or risks that may not be visible when programs are managed individually.
    3. How can alternative capital, or non-bank financing, help address working capital funding gaps? Alternative capital, or non-bank financing, can complement traditional bank funding when organizations need greater flexibility or funding coverage. Combining alternative capital and bank capital can support a broader range of counterparties, regions and risk profiles while creating a more resilient and diversified financing structure.
    4. Why is buyer adoption important to working capital program performance? Working capital programs depend on participation to achieve their intended liquidity and diversification benefits. Simplifying onboarding, reducing friction and clearly communicating program value can help eligible participants successfully enter and use programs.
    5. How does integration support working capital risk management? Greater integration connects systems, data and workflows, helping organizations move from information to action more quickly. Centralized, real-time visibility and portfolio-level intelligence can support more timely, data-driven funding and risk decisions.
  • Simplifying Cross-Border Channel Finance for a Global Supplier​

    Simplifying Cross-Border Channel Finance for a Global Supplier​

    The Challenge

    A major European supplier approaches a Tier-1 bank looking to finance their channel across multiple countries — Portugal, France, Germany, Spain and the Nordic region. The supplier wants to expand across multiple currencies (EUR, GBP, USD, SEK) and activate multiple programs simultaneously.​

    The bank sees the opportunity but faces a structural constraint: the contractual relationship sits in the US (US entities, US bank center), but operations must run from Europe. This mismatch creates friction. The European operating unit does not want to take on the operational burden without the integration infrastructure to support it. The bank also needs C4’s channel financing expertise to enter this market confidently.​

    How C4: Connected Capital Control Center Delivers​

    C4 builds a seamless integration into the bank’s loan platform, including loan creation, clearing, cash entries, accounting entries, interest approvals, trial balances, daily cash clearing and outstanding payment reporting. Everything feeds into their regulatory systems at the right operational level.​

    This integration enables the bank to activate not one program, but five simultaneously acrossmultiple currencies and participating banks – all managed within C4’s portfolio layer.​

    The Portfolio Strength​

    Multiple currencies. Multiple participating banks. Multiple vendor entities. Multiple programs running in parallel. C4 handles concentration checks across all buyer exposures, manages participant bank onboarding and offboarding, and delivers monthly and quarterly reconciliations to zero decimals – fully automated, no manual intervention.​

    Clearing audits, reconciliation and cash management happen seamlessly. Regulatory reportingfeeds directly into the bank’s systems at the right governance level. The bank gets portfolio-levelvisibility and control they could not have built internally.​

    The Results ​

    The bank enters channel finance confidently, scales to five programs across multiple currencies and participating banks and eliminates the operational friction that nearly stopped the deal. C4’s integration and portfolio management capabilities make it possible.​

    Explore C4

    Talk to an Expert

  • Portfolio-Level Transparency for Global Treasury​

    Portfolio-Level Transparency for Global Treasury​

    Overview​

    • Program:  Multi-funder working capital program for global treasury​
    • Client:  Large multinational distributor ​
    • Structure:  Funder-neutral servicing platform with centralized control​
    • Complexity:  Multiple buyers, banks and non-bank funders across global jurisdictions​

    The Challenge

    A multinational enterprise operating across a fragmented global funding environment needs to balance liquidity, pricing and funding flexibility across multiple working capital programs without increasing operational burden, delays or compliance risk.​

    As funding relationships expand across banks, non-bank funders and regions, treasury visibility becomes increasingly fragmented. Funding decisions rely on disconnected systems, spreadsheets and periodic reconciliations, limiting the ability to evaluate liquidity, pricing and exposure across the portfolio in real-time.​

    The operating model is no longer built for the scale and structural complexity the business has grown into.​

    How C4: Connected Capital Control Center Delivers​

    GSCF deploys two integrated components that give Treasury centralized control withoutrebuilding their internal infrastructure.​

    1.  One Fully Integrated Platform with Portfolio-Level Visibility 

    A purpose-built workflow that gives Treasury centralized oversight and control across all workingcapital programs:​

    • Approve and route funding requests through one platform​
    • Optimize capital efficiency with consolidated visibility into usage, availability and cost​
    • Make faster, data-driven decisions with real-time program and pricing views​
    • Reduce manual consolidation and reporting​

    2. Funder-Neutral Servicing Platform

    A single operational layer connecting the enterprise to buyers, banks and non-bank funders globally:​

    • One access point for all programs: connect once to operate across multiple buyers, banks andfunders​
    • Standardized workflows across jurisdictions: consistent processing across countries, currencies andlocal requirements​
    • Faster payments, less administration: streamlined submission, validation and approvals reduce delays and rework​
    • Format and protocol flexibility: EDI/CSV/XML and API/AS2/SFTP/web upload, with built-innormalization across ERP systems​
    • Built-in, customizable compliance and validation: program and funder specific rules to reducerejects and exceptions​
    • Full visibility and tracking: real-time status across programs with audit trails and reporting​
    • Bank and funder flexibility without disruption: add or switch funders with minimal operational change​

    How the Relationship Evolves​

    As funding structures and regional complexity expand, C4 becomes the connective operational layeracross the enterprise’s broader working capital ecosystem.​

    Treasury gains dynamic visibility into liquidity, pricing and exposure across funding sources while regional teams continue operating within established local workflows. The operating model scales globally without requiring proportional increases in operational overhead.​

    The Results ​

    Treasury gains the visibility and flexibility needed to manage working capital as a connected global portfolio rather than individual, disconnected programs.​

    • Centralizes visibility across funding structures, pricing and liquidity​
    • Faster funding decisions supported by real-time portfolio insight​
    • Reduces operational friction and manual reconciliation​
    • Greater flexibility to add or transition funding partners​
    • Scalable global infrastructure without increasing operational complexity​

    Explore C4

    Talk to an Expert

  • GSCF Launches C4: Connected Capital Control Center

    GSCF Launches C4: Connected Capital Control Center

    Delivering Visibility and Control to Corporates, Banks & Asset Managers

    RELEASE DATE: 26 March, 2026, 9:00 am EDT   

    NEW YORK, March 26, 2026 – GSCF, a leading global provider of working capital solutions, today announced the launch of Connected Capital Control Center (C4) – a servicing platform designed to help banks, asset managers and enterprise corporates originate, manage and analyze working capital with greater visibility, control and confidence across multiple programs.

    Built to support GSCF’s Connected Capital ecosystem and the broader market landscape, C4 addresses a growing market need: organizations are deploying multiple working capital programs across regions, funders, insurers and service providers, yet lack a single source of truth to track exposure, liquidity, cost and risk across their entire portfolio of programs.

    C4 consolidates program data and workflows into one unified control layer for programs serviced by GSCF or external providers, enabling financial institutions and enterprises to scale working capital more efficiently while reducing operational friction and risk.

    “As working capital portfolios grow more complex, fragmented views and manual oversight aren’t sustainable,” said Doug Morgan, Chief Executive Officer of GSCF. “C4 brings portfolio-level clarity to enterprises and their funding partners – so decisions can be made with confidence, limits can be enforced proactively, and working capital can be deployed more strategically across the global ecosystem.”

    C4 for Enterprise Corporates: Advanced Intelligence for the Office of the CFO
    For global enterprises relying on multiple working capital programs across regions, funders and administrators to drive liquidity and fuel growth, C4 provides a single, aggregated view of all working capital activity to eliminate data silos and enable centralized oversight.
    Key capabilities for corporates include:

    • Aggregated Data Views: A single source of truth consolidating all working capital programs, regardless of funder or platform
    • Portfolio-Level Intelligence: Holistic visibility across regions, buyers, suppliers and counterparties to support CFO- and Treasurer-level decisioning
    • Cross-Funder Transparency: Clear insight into funding flows, utilization and pricing across multiple banks and capital partners
    • Global Operational Workflows: Standardized and automated processes designed for multi-region, multi-funder environments
    • Exposure and Concentration Management: Program- and portfolio-level analytics to identify risk, adjust limits and optimize capital allocation

    By unifying data and decisioning at the portfolio level, C4 allows enterprises to move beyond reactive reporting and manage working capital as a strategic asset.

    C4 for Banks: Scaling Working Capital with Confidence and Control
    For trade finance and structured working capital teams, C4 delivers real-time visibility and embedded controls across multi-program and multi-funder portfolios to enable faster origination, stronger governance and scalable growth.
    Key capabilities for banks include:

    • Portfolio-Level Visibility: A consolidated, real-time view of exposure across obligors, regions, insurers and structures
    • Built-In Limit Management: Embedded credit limits, concentration thresholds, alerts and automated “pause” mechanisms
    • Streamlined Accounts Receivable: Standardized AR processes that scale from simple programs to complex, insured structures
    • Co-Origination and Extended Capacity: A unique combination of servicing expertise and funding capabilities that expands balance-sheet flexibility

    C4 empowers banks to shift from a model of program-by-program oversight to true portfolio management, reducing blind spots while increasing confidence in the ability to grow with efficiency and discipline.

    A Control Center Built for Scale, Not Silos
    Unlike today’s working capital landscape that can be fragmented across operations, technology and data, C4 is designed as a portfolio-level control layer that integrates technology with GSCF’s world-class managed services. Backed by more than 30 years of experience operating complex working capital programs globally, GSCF embeds operational precision directly into the platform – allowing clients to offload complexity while fully retaining control.

    “C4 addresses the needs of banks and enterprises today while supporting their growth across multiple programs, partners and jurisdictions,” said Shannon Dolan, Chief Product Officer of GSCF. “By consolidating data, limits, workflows and decisioning into one control center, C4 will help teams act faster, reduce risk and continuously optimize working capital performance at scale.”

    “The evolution of working capital management is moving beyond process efficiency toward liquidity orchestration. As enterprises and their financial partners deploy programs across an increasingly complex ecosystem of funders, regions and structures, the demand for portfolio-level visibility and control is intensifying. C4 reflects where the market is heading – a unified control layer that enables CFOs and Treasurers to manage liquidity not just as an operational necessity, but as a driver of business performance and resilience,” said Senior Research Director, IDC Enterprise Applications, Kevin Permenter.

    About GSCF

    GSCF is the leading global provider of working capital solutions. The Company enables corporates and financial partners to accelerate growth, unlock liquidity and manage the risk and complexity of the end-to-end working capital cycle. We originate, manage and analyze working capital programs through our innovative Working Capital as a Service offering, combining the power of a configurable and comprehensive technology platform, expert services and a Connected Capital ecosystem of alternative capital solutions and bank capital. GSCF’s team of working capital experts operates in over 75 countries to solve global working capital efficiency challenges. Visit www.gscf.com to learn more.

  • From Revolver Strain to Strategic Flexibility: How Growth Corporates Unlock Liquidity

    From Revolver Strain to Strategic Flexibility: How Growth Corporates Unlock Liquidity

    Growth companies face a constant balancing act. On one hand, sponsors demand aggressive expansion; on the other, lenders watch leverage and liquidity closely. Too often, CFOs and treasurers are forced to use their revolver for routine working capital needs—when that facility should be reserved for strategic initiatives or true emergencies.


    That’s where alternative capital solutions come in. By unlocking liquidity trapped in receivables and payables, finance leaders can take pressure off their revolvers, maintain sponsor confidence, and keep capital available for growth or M&A activity.

    The Revolver Pressure Problem
    Consider a mid-sized telecom company scaling digital services while investing in IT infrastructure. Despite strong growth, day-to-day liquidity needs forced repeated revolver draws, triggering concerns from its lenders. By introducing a receivables financing program, the company freed up liquidity without touching the revolver, preserving borrowing capacity for expansion.
    In another case, a packaging manufacturer growing in pet food faced earnings volatility after a customer bankruptcy. Alternative capital solutions allowed the CFO to fund M&A activity without leaning on the revolver, improving optics with both sponsors and creditors.

    Growth Without Revolver Dependency
    A European industrial group recently implemented a payables finance program across divisions, creating liquidity to fund transformation initiatives while keeping its revolver fully available. This not only improved the company’s balance sheet optics but also reassured lenders ahead of a potential exit event.

    Meanwhile, a global packaging firm carrying high leverage had access to an unused ABL facility, but its rigid terms offered little flexibility. By shifting to an alternative capital program, the CFO unlocked faster, more flexible working capital while maintaining revolver headroom for larger, strategic needs.

    Strategic Growth Requires Strategic Capital
    From tech acquisitions to supply chain expansions, strategic moves require working capital that can be deployed quickly and flexibly. Alternative capital makes this possible by funding growth through receivables and payables programs, not revolver draws – strengthening balance sheet optics and preserving sponsor confidence.

    Why Now?

    • Economic and geopolitical uncertainty, volatile supply chains and postponed IPOs all make traditional financing less reliable. The Office of the CFO needs solutions that are:
    • Resilient: Liquidity that flexes with growth cycles
    • Responsive: Working capital that deploys quickly when opportunities arise
    • Non-dilutive: Funding that avoids tapping the revolver or adding leverage

    Swap Revolver Strain for Alternative Capital
    If your company is relying on revolver draws to fund working capital, it’s time to explore GSCF’s alternative capital solutions. These solutions unlock liquidity, preserve borrowing capacity, and give CFOs and treasurers the flexibility to grow on their terms.rnative capital solutions. These solutions unlock liquidity, preserve borrowing capacity, and give CFOs and treasurers the flexibility to grow on their terms.

  • The Office of the CFO’s Top 10 Checklist for Simplifying Working Capital Complexity 

    The Office of the CFO’s Top 10 Checklist for Simplifying Working Capital Complexity 

    For today’s Office of the CFO, complexity isn’t the exception. It is the operating reality. Shifting trade policies, fragile supply chains and managing across jurisdictions have made working capital management a tangled web. But complexity doesn’t have to be chaos. 

    Here is a practical checklist finance leaders can use to bring clarity, speed and control to working capital strategy without overhauling their entire infrastructure. 

    1. Map Your Complexity 

    Document all legal entities, geographies, systems and supply chain touchpoints that affect working capital. This baseline will guide every integration and improvement decision. 

    2. Unify Platforms Without Rip and Replace 

    Focus on integration, not disruption. Connecting existing platforms can centralize key data and processes faster than a full technology overhaul. 

    3. Streamline Cross-Functional Workflows 

    Align finance, sales, technology and operations on shared KPIs. A single source of truth improves decision-making and reduces delays. 

    4. Automate High-Friction Processes 

    Target manual processes in AR, AP and reporting. Even partial automation can free resources and improve accuracy. 

    5. Standardize Supplier and Buyer Data 

    Inconsistent onboarding, payment terms and documentation slow cash flow. Create templates and enforce them globally. 

    6. Embed Risk Mitigation in Working Capital 

    Integrate credit insurance tracking and exposure monitoring into workflows to avoid costly gaps. 

    7. Prioritize Execution Visibility 

    Identify and address local market bottlenecks early. Visibility at the execution level prevents small issues from escalating. 

    8. Build Playbooks for Special Cases 

    Non-disclosed financing and indirect payment arrangements require specialized processes. Pre-approve workflows to save weeks during execution. 

    9. Measure What Matters 

    Focus on liquidity, cycle times and cost of capital as leading indicators, not just lagging performance metrics. 

    10. Challenge Your Providers 

    Test their ability to deliver speed, flexibility, and tailored solutions. The right partner should meet your needs in real time. 

    Bottom line: Complexity will keep increasing, but with the right checklist, the Office of the CFO can turn it into a competitive advantage. For more insight, download the GSCF’s eBook, Simplifying Complexity in Working Capital Management: A Guide for the Office of the CFO.